Report August 2026

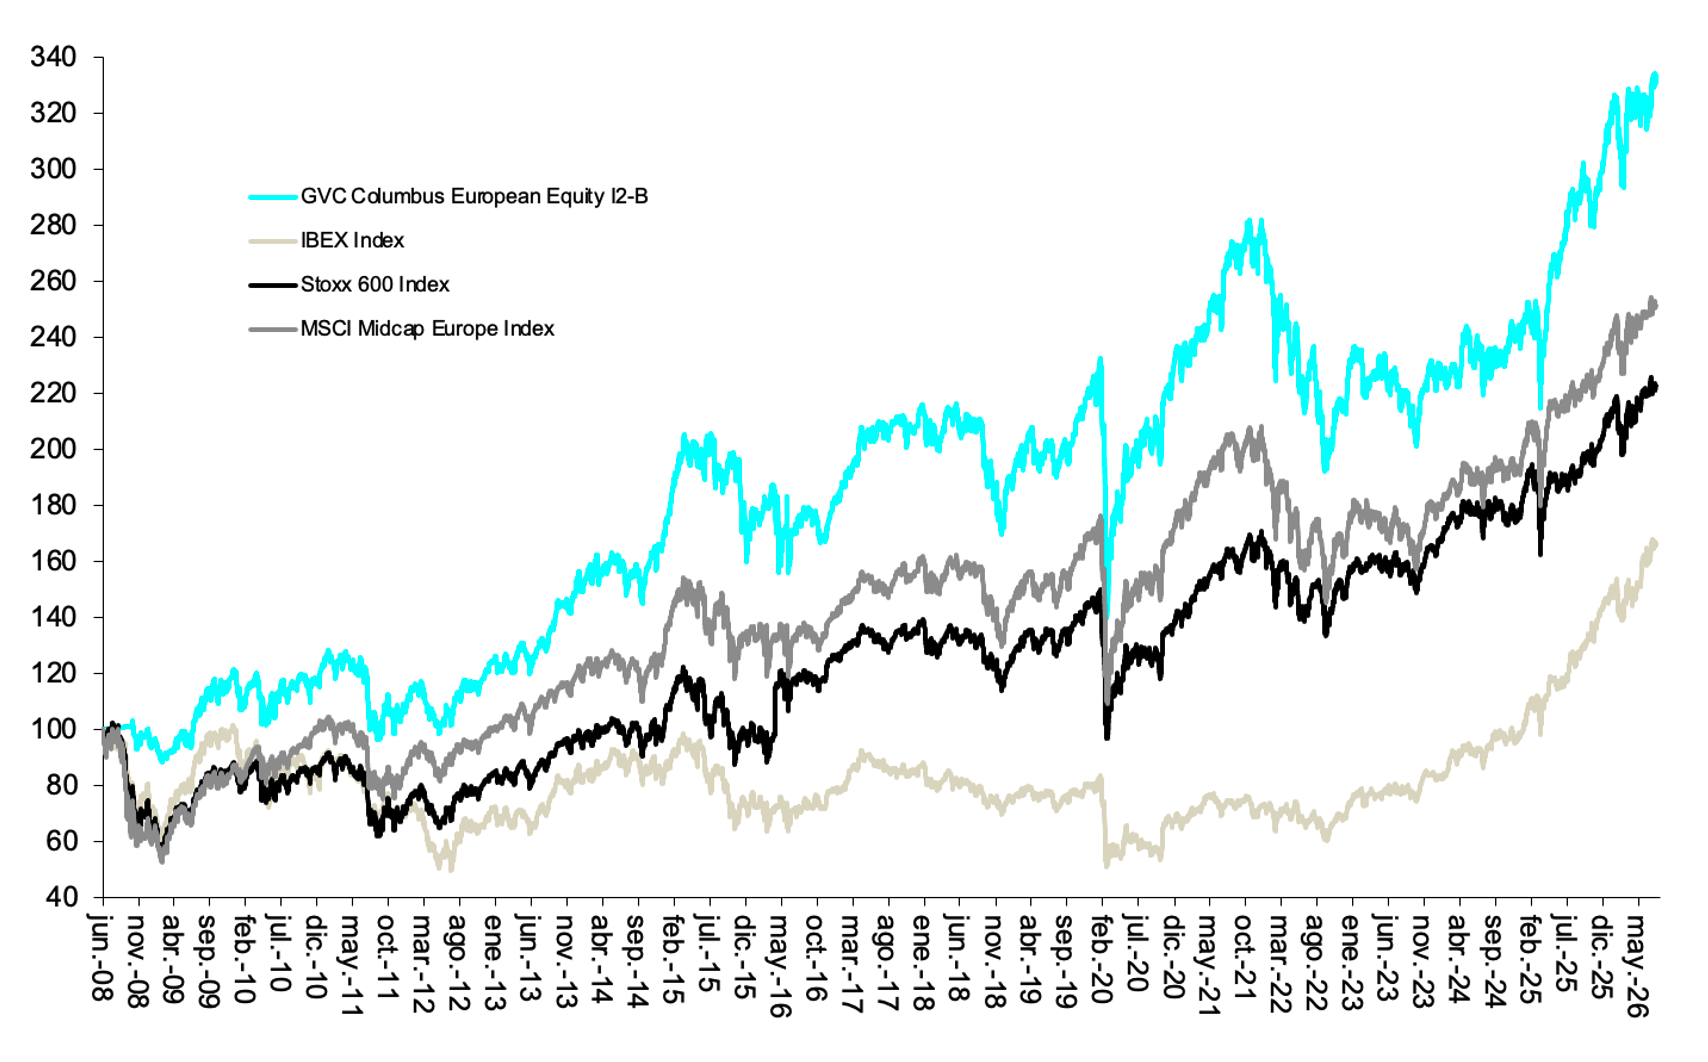
Performance: During August, the Pareturn Columbus Class I2 fund rose by 2.76%. Since the start of the year, it has risen by 9.72%. Over the last 12 months, the fund has recorded a cumulative rise of 15.3%. Columbus ranks in the top quartile of its category over 3- and 5-year periods, according to Morningstar data. Since its launch in June 2008, the fund has recorded a cumulative return of 247%, consistently outperforming the main European stock market indices.
Market environment: August was a month of sharp reversals, leaving the STOXX 600 broadly unchanged but masking significant dispersion beneath the surface. The index reached a record high mid-month before geopolitical developments, a semiconductor selloff and sharply higher sovereign yields erased the gains. The DAX rose 1%, the FTSE 100 was little changed and the CAC fell 3.2%, while Basic Resources gained 9.4% and Food, Beverage and Tobacco lost 4.7%.
Leadership also rotated sharply: July’s winners, Energy and Banks, lagged, while Growth outperformed Value by c.175bps and Technology recovered strongly. Outside equities, European sovereign bonds were the month’s defining move, with the OAT-Bund spread widening beyond BTP-Bund for the first time this cycle and the Bund yield rising 21bps.
Performance of key holdings:
During August, Bodycote’s rise (+26%) stood out. The British hot metal treatment company announced at the start of the month that it had received two separate and independent takeover bids from private equity firms. One of them, Veritas, improved its initial bid by a further 4% at the start of September. The interest in Bodycote reflects the interest shown by foreign investors, particularly US private equity firms, in British companies, which are trading at lower valuations, making them attractive targets.
The two telecoms’ companies in our portfolio, Zegona (+11.6%) and 1&1 AG (+17.6%), also saw sharp rises. The rise was driven by a rotation towards defensive and value sectors, solid quarterly results and ongoing corporate activity in the sector.
On the downside, Fresenius Medical Care fell by 11%. Although Fresenius exceeded general expectations in terms of total profits, the market focused on a key operating indicator: treatment volumes in the US market fell by 0.9% year-on-year. Given that the US is Fresenius’s largest and most lucrative market, this decline raised concerns amongst investors regarding long-term underlying demand.
Download monthly factsheet [PDF]
Since May 2023, Spanish investors can access the Columbus strategy through the Spanish fund GVC Columbus European Equities FI. The Fund can be purchased through the AllFunds, Inversis and Fundsettle platforms. Columbus has a Master-Feeder structure. The Pareturn GVC Gaesco Columbus European Equity Fund in Luxembourg (master) and the GVC Columbus European Equities FI (feeder). The Luxembourg vehicle offers institutional and retail share classes denominated in euros and sterling.